Our Big Break(s)
2006–2010 · Nottingham, Expanding to the capital
creo:media becomes Distinction, our first 'big brand' clients land, and the iPhone rewrites every brief.
Rebrand from creo:media to Distinction
2006
By the back half of the decade, creo:media had outgrown its name. So, we became Distinction - the name we've carried ever since. It marked a shift in how we saw ourselves: less of a small studio finding its way, and more a leading agency with a clear point of view about creating great work.
Move to The Lace Market
2006
Closer to home, we moved the Nottingham office out of West Bridgford and into The Lace Market, which became our home for many years.
AWS invents modern cloud
2006
In 2006 Amazon Web Services invented and launched the modern cloud. It was the start of a new era for digital infrastructure, and reshaped how businesses operate.
Our first 'big brand' clients
2007
Working with mid-sized firms has always been our core, but in the early years we also pitched for and won work with brands our friends and family knew - Unilever, Barclays, Ford, BMW, Speedo and Confused.com among them. For a young agency, landing brands of that size was the moment things started to get serious. We continue to work with some of them 20 years later.
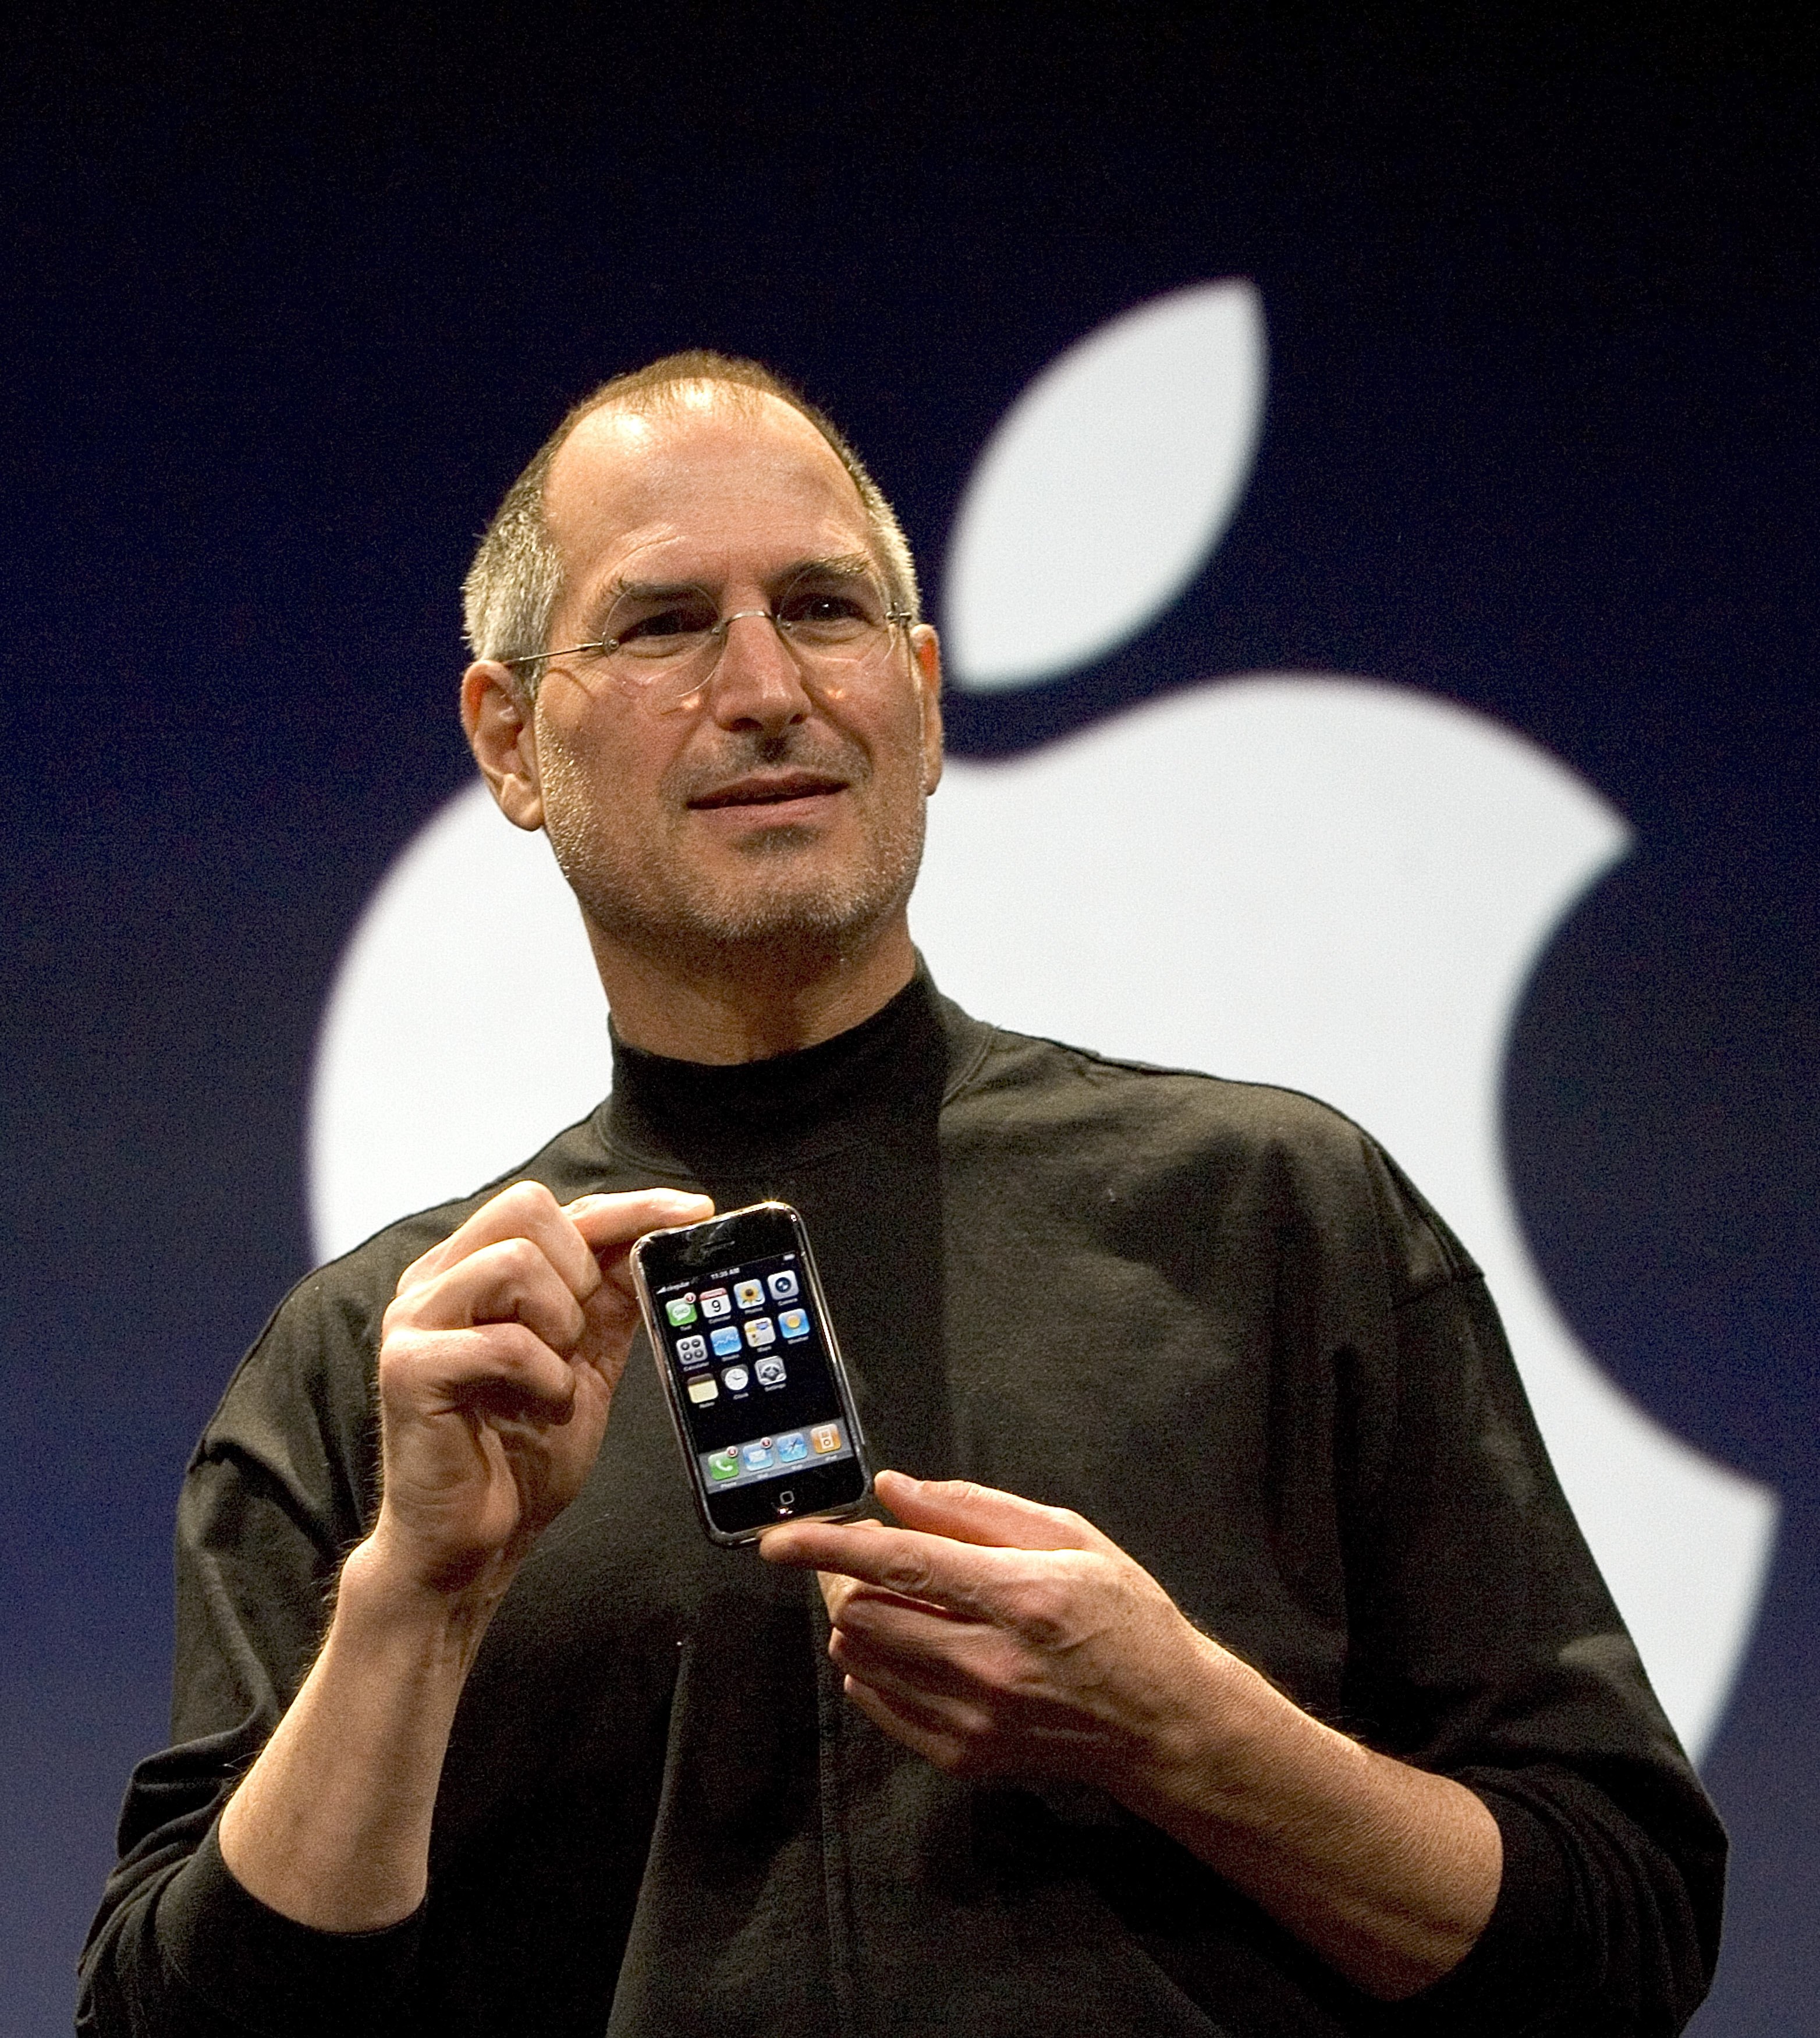
iPhone unveiled
2007
The iPhone arrived in 2007, the hinge the whole era turns on. Over the next few years, Apple rewrote the brief for every digital project, and changed how people thought about the web, mobile and apps.
Team of five and a London office
2008
We grew to a team of five and opened a London office as more work started coming from the capital. It was the first sign that we weren’t going to stay as a small local firm.
Global financial crisis
2008
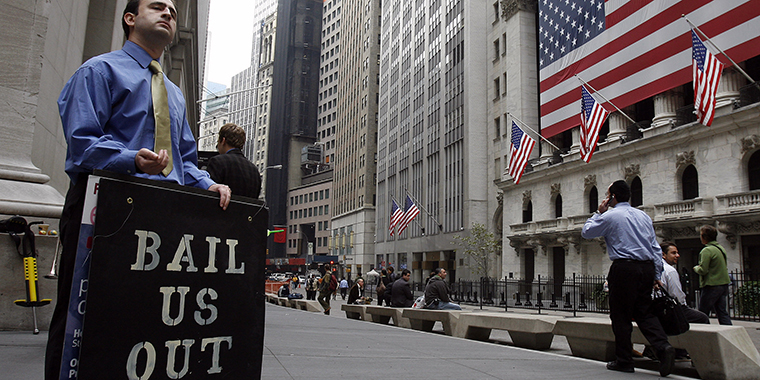
In 2008 Lehman Brothers collapsed and the bailouts began in earnest. The global financial crisis reshaped the world economy and the way people thought about money.
2008 - 2009 Cultural Moments
2008
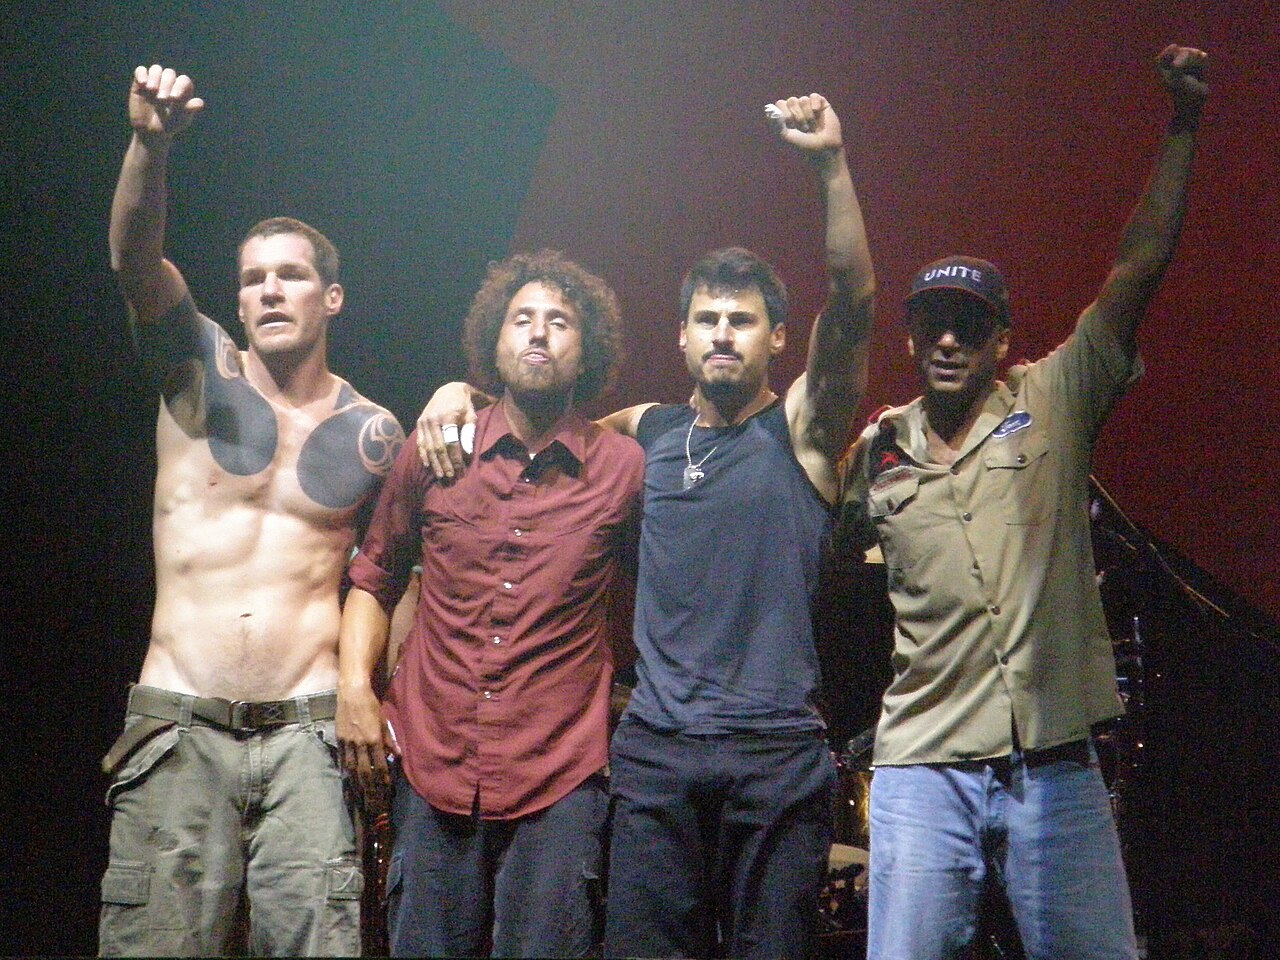
Culture (2008-09): Avatar smashed box-office records, iPlayer changed how Britain watched, and Rage Against the Machine beat the X Factor to Christmas number one.
2006 - 2010 Sporting Moments
2008
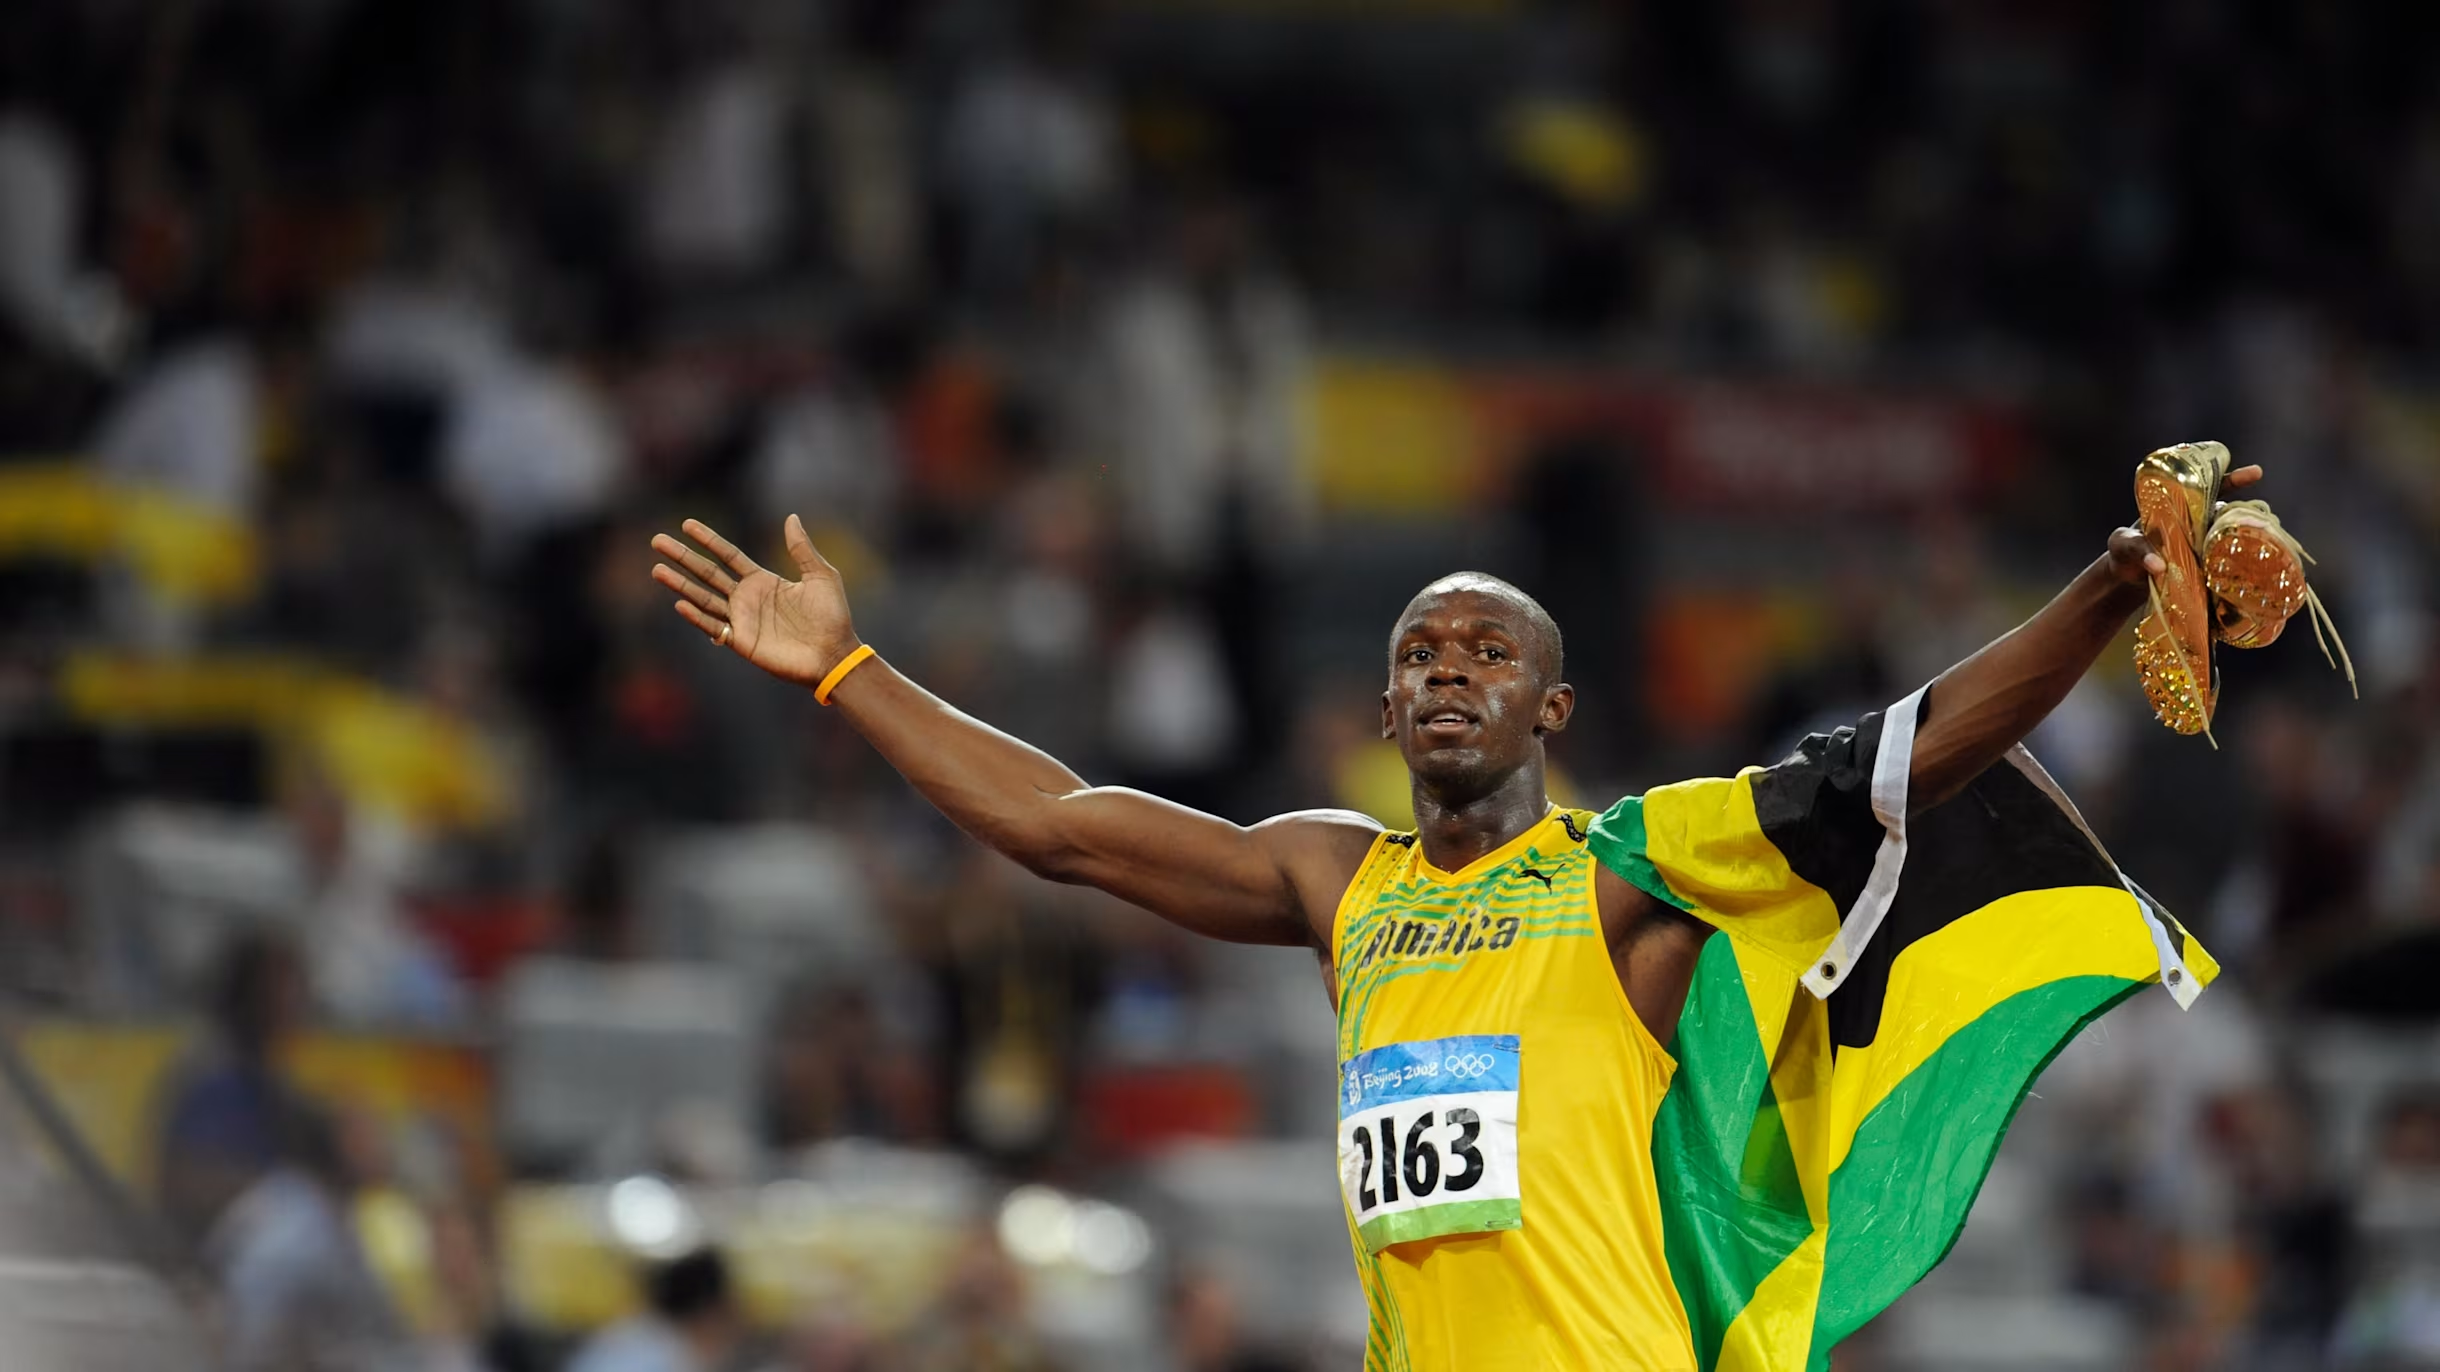
At Beijing 2008, Usain Bolt and Michael Phelps lit up the Olympics.
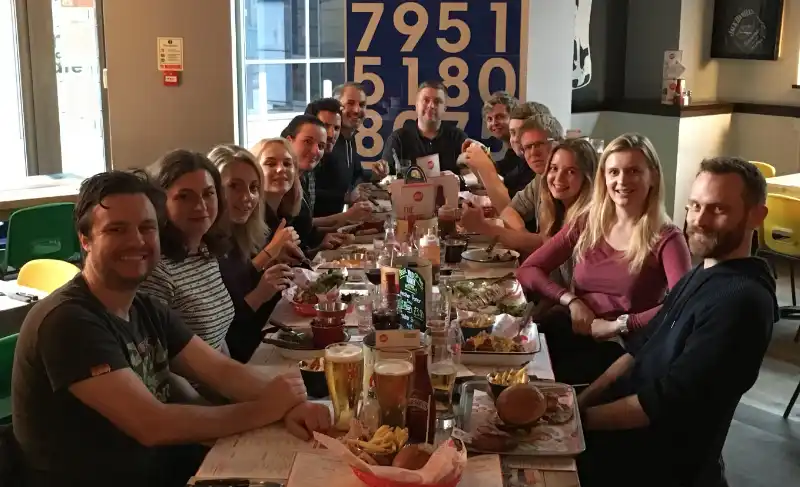
The people behind the early growth
2008
Behind the client wins were the people who built them. Matt O, our first technical hire, is still with us 5 years later.
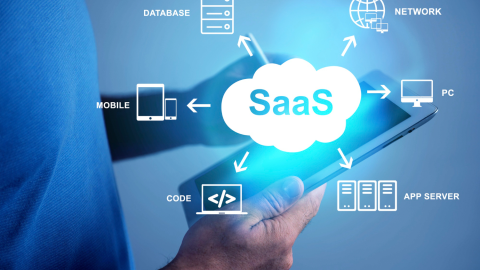
SaaS grows up
2009
By 2009 software-as-a-service was pitched as the future. Companies like Salesforce, Dropbox and Concur were changing how software was built, sold and consumed.
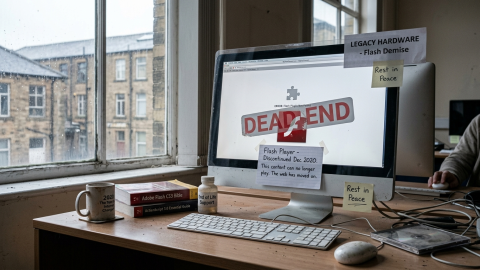
Death of Flash
2010
Starting in 2010, Apple and Steve Jobs started to write off Flash, with HTML5 taking its place. Almost overnight, the way interactive content was built and delivered changed forever. Flash developers found themselves out of work, having to upskill quickly to stay relevant. Sound familiar?
Finding Our Feet
2011–2015 · Nottingham, On the move, again
A fast-growing team, award-winning work, and the range to take on bigger, harder briefs.
Moving again
2011
The team grows fast, as so we move again into a larger office in Nottingham. We were no longer the scrappy few; we had the range to take on bigger, more complicated briefs.
Capital One and Pan Macmillan
2011
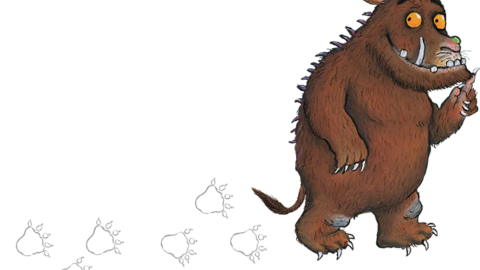
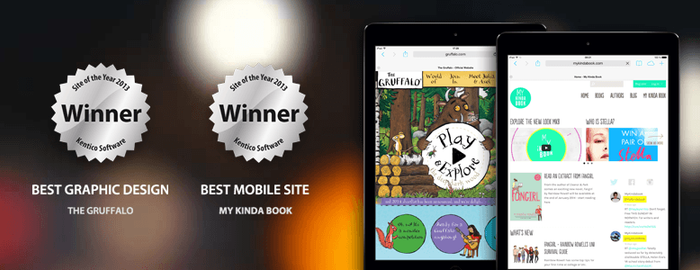
New big client names joined the roster, including Capital One, Direct Line Group, University of Nottingham, and the start of a long relationship with Pan Macmillan. We've very fond memories of working on The Gruffalo.com, which was a huge hit with kids and parents alike, and won a Kentico Site of the Year award in 2014.
Instagram, Snapchat, Pinterest
2011
Between 2010 and 2011 Instagram, Snapchat and Pinterest reshaped how people shared and interacted online. Also bringing new ways for companies to market and engage with audiences. The way we thought about social media changed forever.
Responsive web / mobile-first
2011
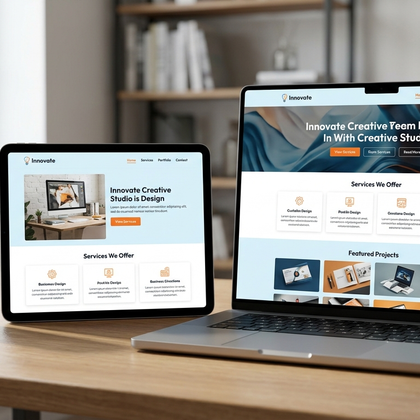
Around 2011 responsive design was coined and "mobile-first" became the mantra. The web was no longer a single screen, and the way we designed and built digital experiences changed forever.
Siri and Alexa
2011
Siri arrived in 2011, then Alexa in 2014, and voice got interesting. You could argue that voice is still an emerging technology, often temperamental, but it’s certainly a mainstream part of our lives.
Digital transformation enters
2011
Around 2011 "digital transformation" entered the corporate lexicon, and the consultant invoice. It was the start of a decade-plus-long trend of companies trying to become more digital.
2011 - 2015 Sporting Moments
2012
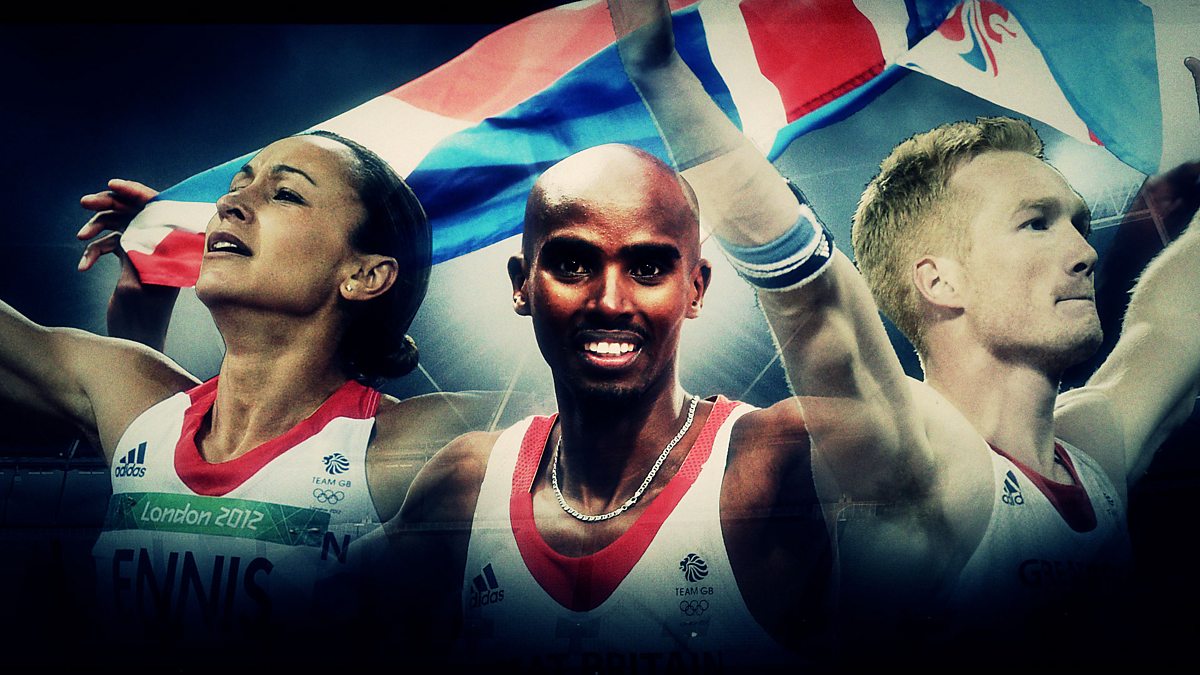
London 2012 gave us Super Saturday; Murray won Wimbledon in 2013. Arguably the British sporting highs of the decade.
Award-winning work
2013
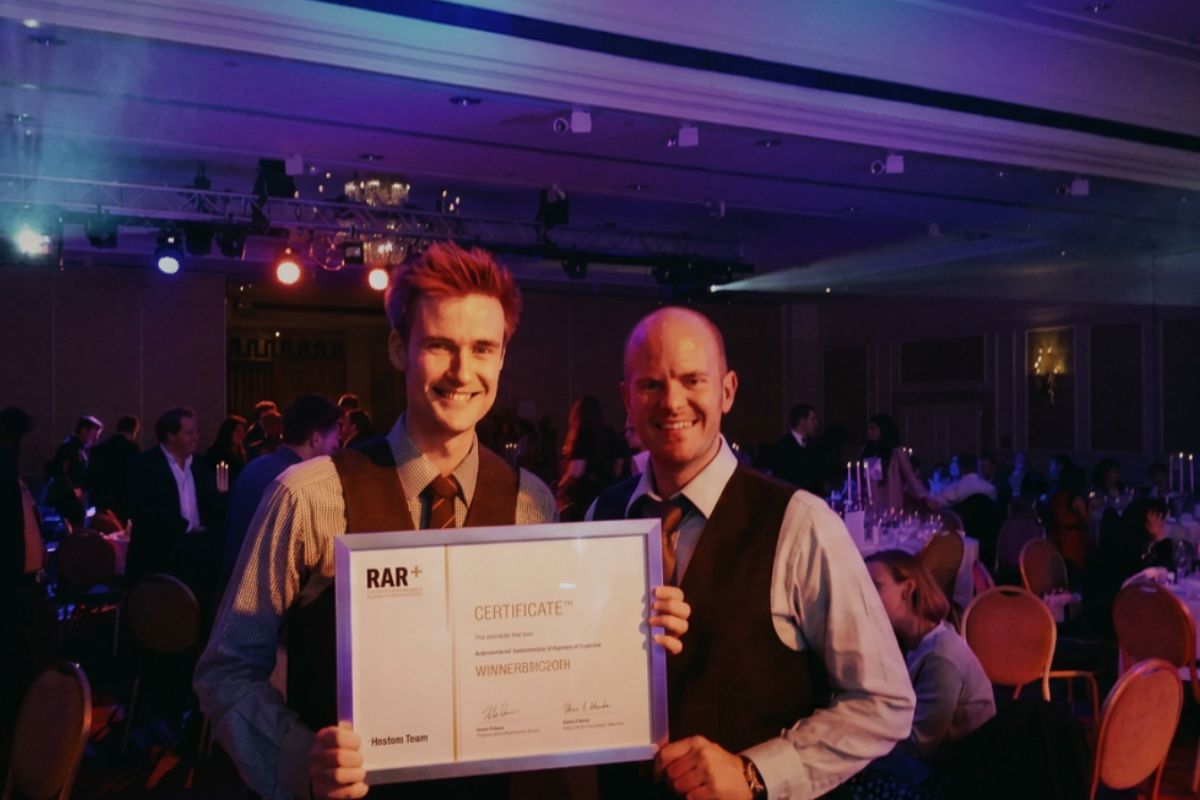
We started to enter and win awards - We won our first two Kentico Site of the Year awards for our work with Pan Macmillan. And two RAR awards followed in 2015 (we've now won more than 20 of them in total).
Personalisation expectations climb
2013
By 2013 Amazon and Netflix made personalised recommendations feel completely normal. The bar for personalisation was set, and the expectation for it climbed.
2011 - 2015 Cultural Moments
2014
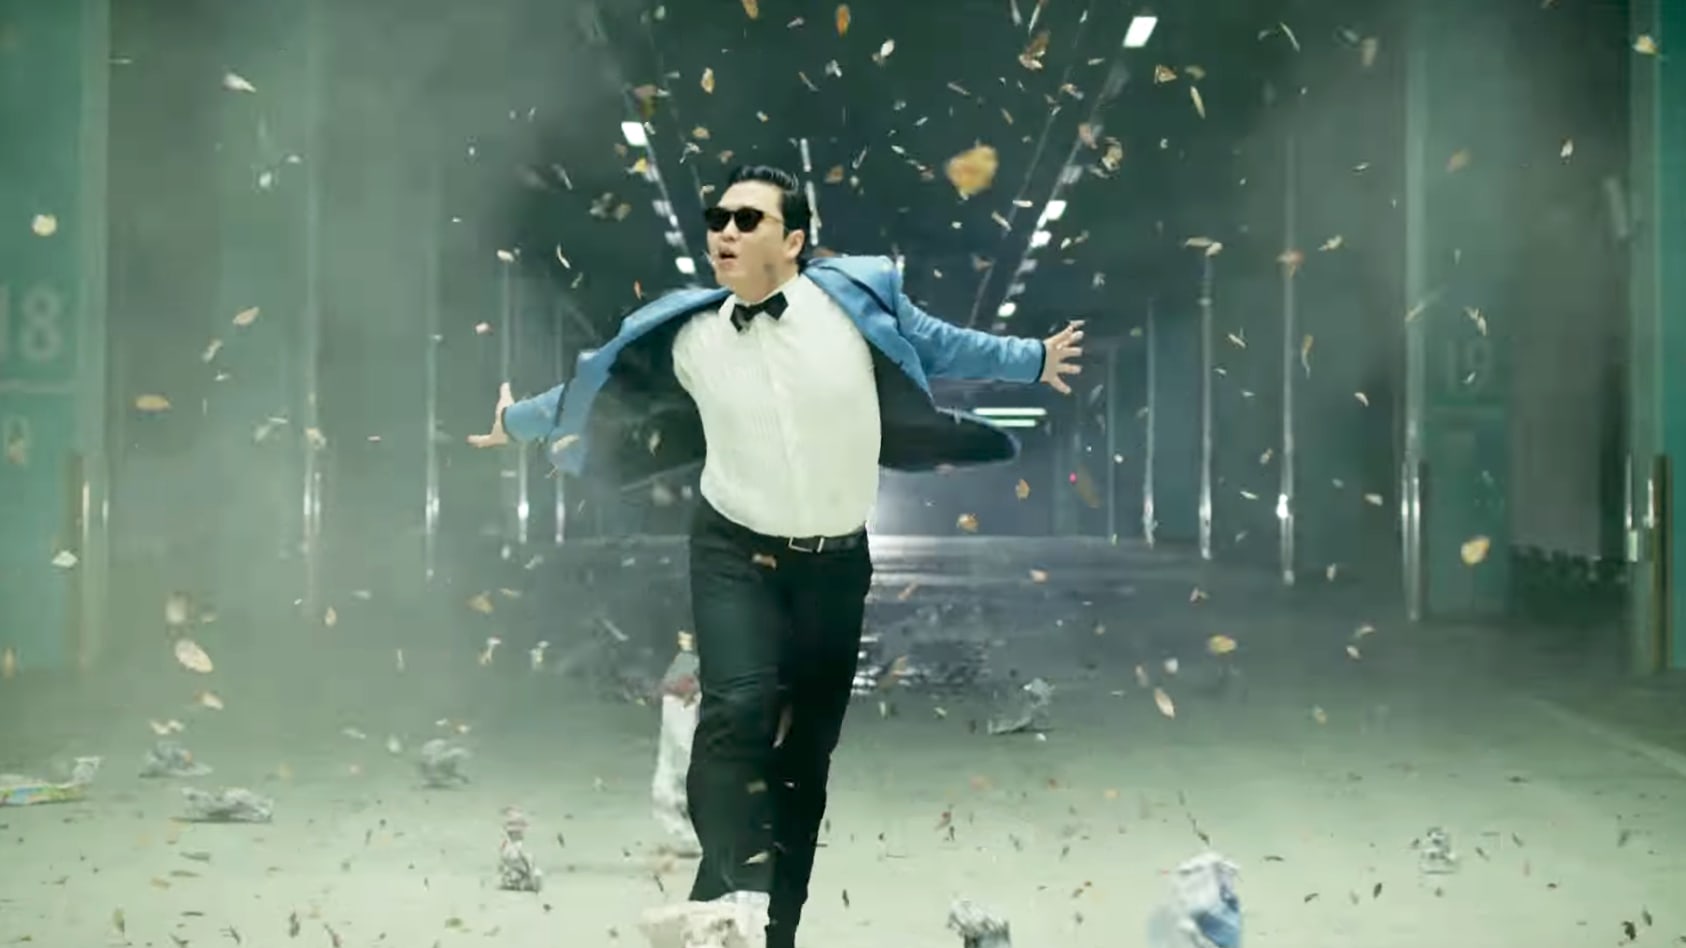
Gangnam Style became the first billion-view YouTube video, House of Cards launched the streaming-original era, and the Ice Bucket Challenge wrote the viral-charity playbook.
A wall full of awards
2015
By 2015 we'd won 2 Kentico Site of the Year awards and 6 Recommended Agency Register awards - putting us among the most decorated agencies of our size in the UK. We were most proud of our 'Most Effective' RAR award, because it was judged on outcomes over outputs. A mantra we still live by today.
Coming of Age
2016–2020 · Going International, Expanding to the US
Thirty strong with a foot in the US - then a year that moved everyone online overnight.
15 not out
2016
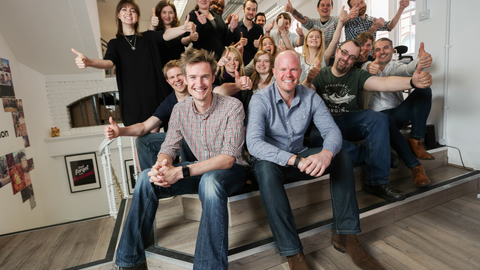
We continued to grow to nearly 30 people – an A-Team of strategists, developers, marketers, designers and project managers working as one joined-up team. We moved, again, and commissioned Geo Law to create a custom wall doodle to commemorate.
US expansion
2016
To meet growing demand from across the pond, we expanded operations to the US in 2016, opening our first US office. That marked the first steps to us becoming an international business.
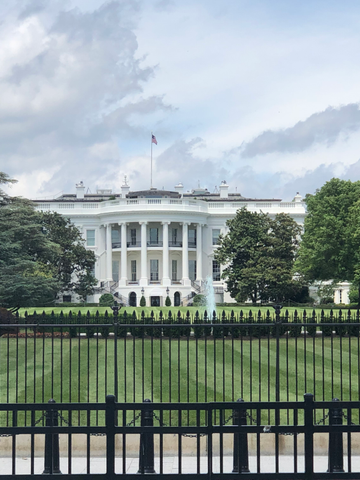
AlphaGo beats Lee Sedol
2016
In 2016 AlphaGo beat the world's best Go player, and AI felt real. It was a watershed moment for AI, and the start of a new era in machine learning.
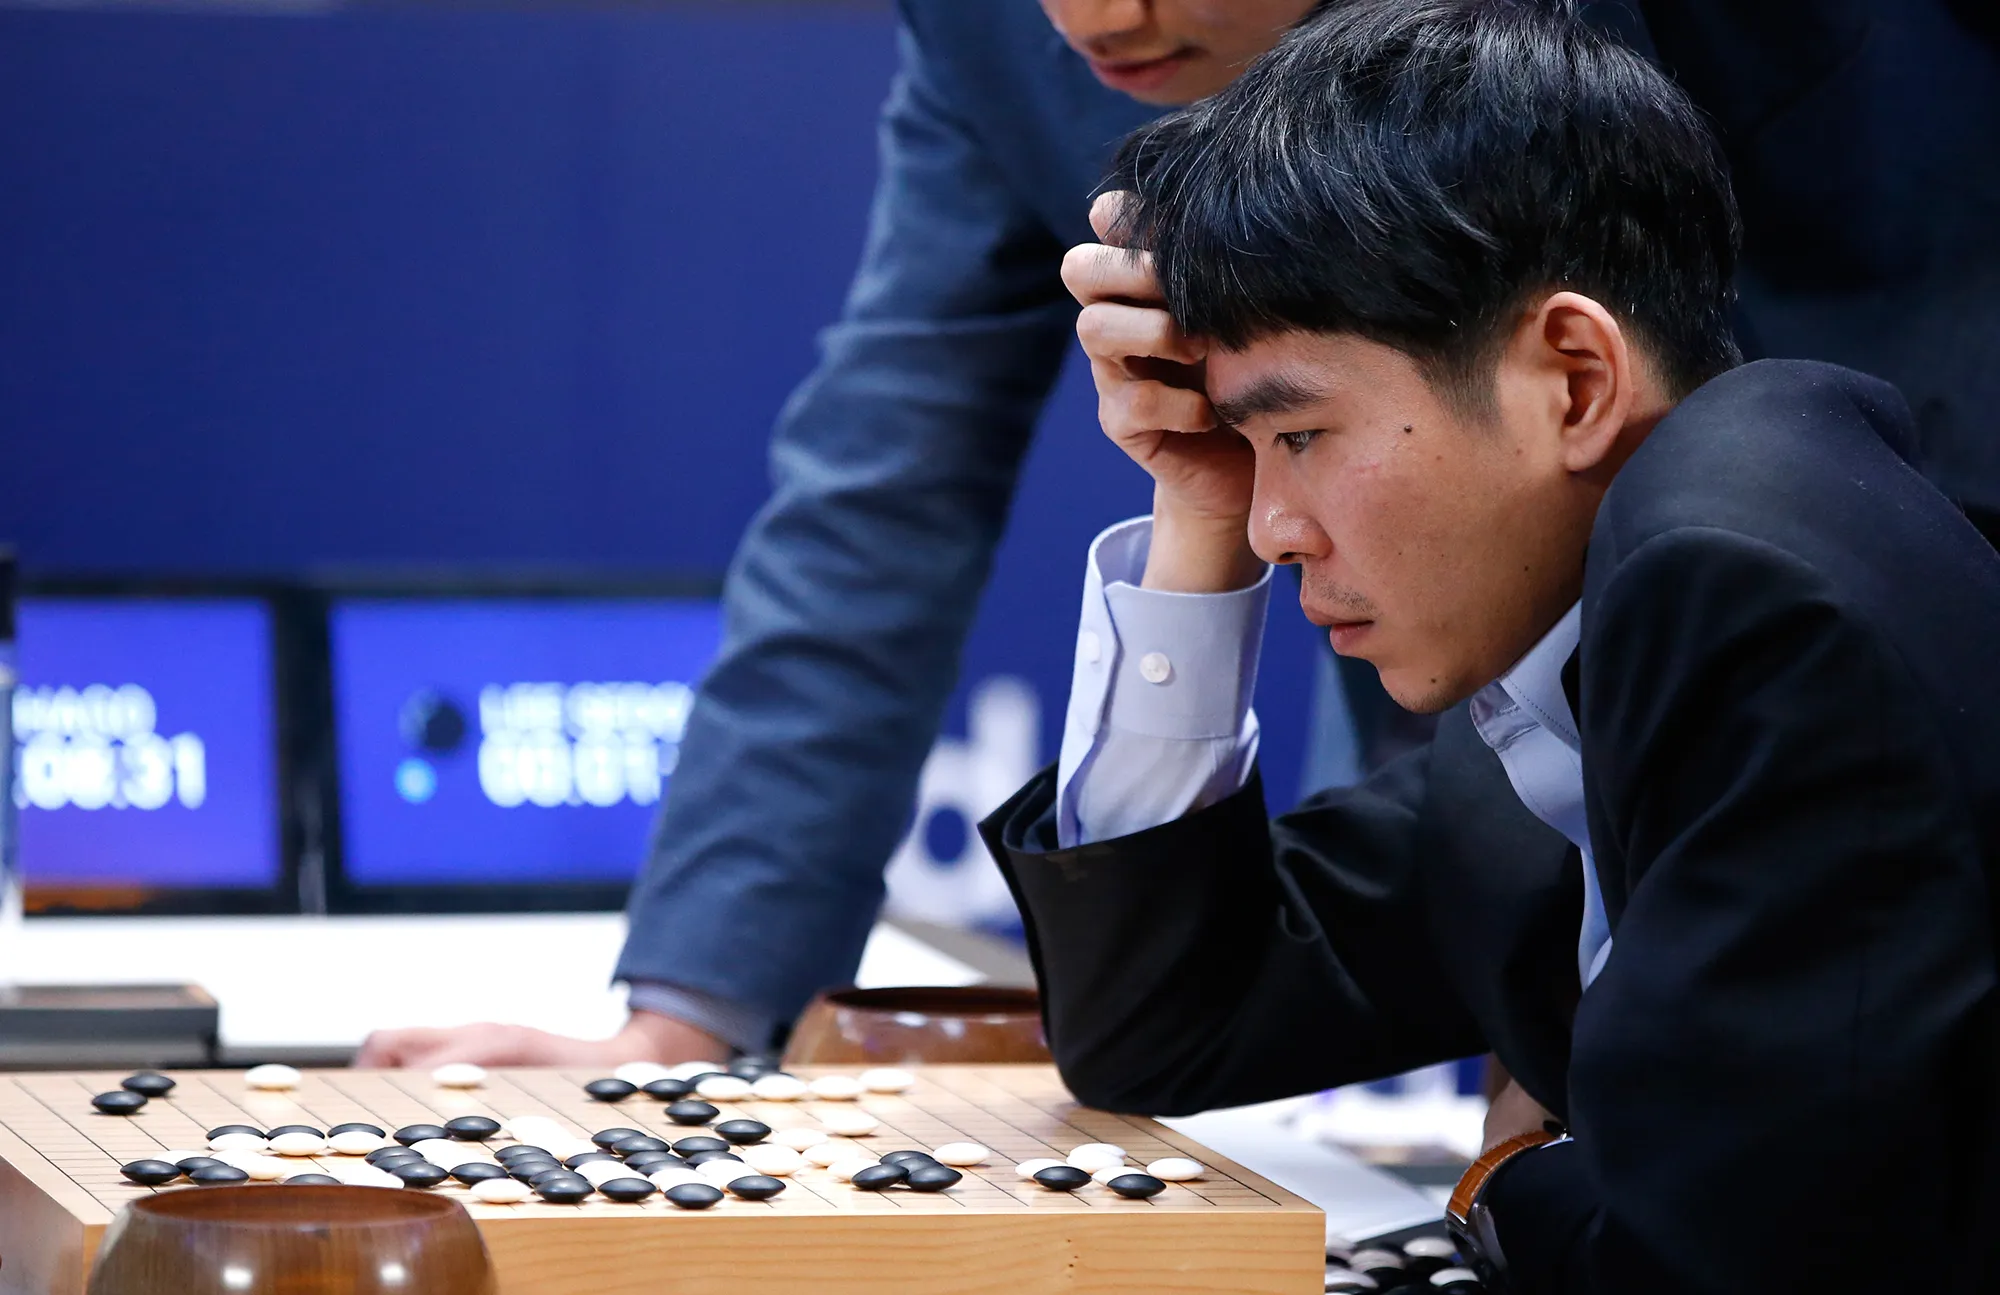
Brexit and Trump
2016
2016 brought us both Brexit and confirmation of President Trump's first term. A turbulent year, no doubt. The world was changing fast, and the way people thought about politics, media and information was shifting too.
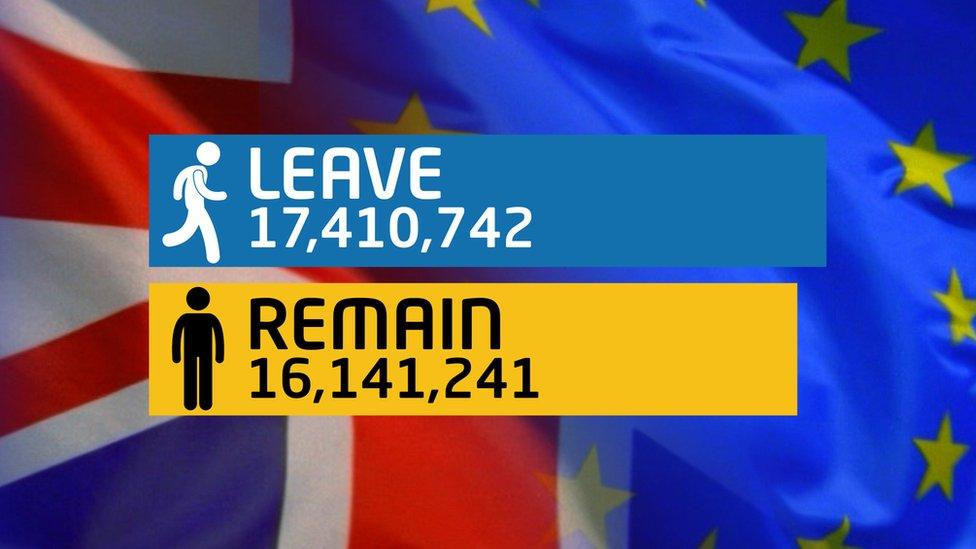
Sport
2016
In 2016 Leicester won the Premier League at odds of 5,000:1. Perhaps one of the greatest underdog stories in sports history, led by the 'Tinker Man' Claudio Ranieri. Proving once again that a good team beats a collection of individuals every time.
TikTok goes global
2018
From 2018 TikTok went global and rewrote the rules of attention. The app’s algorithmic feed and short-form video format made it a cultural phenomenon, and a new way for brands to reach audiences.
GDPR comes into force
2018
GDPR arrived in 2018 and cookie banners bred across the entire web. Even now, it’s still a hot topic for brands and marketers, and a reminder of the importance of data ethics.
Cambridge Analytica
2018
The 2018 Cambridge Analytica scandal made data ethics a board-level worry.
Accessibility climbs the agenda
2018
By 2018 accessibility finally climbed the agenda as legal cases grew teeth. We were already ahead of the curve, and our accessibility-first approach to design and development became a key differentiator for us.
Culture
2018
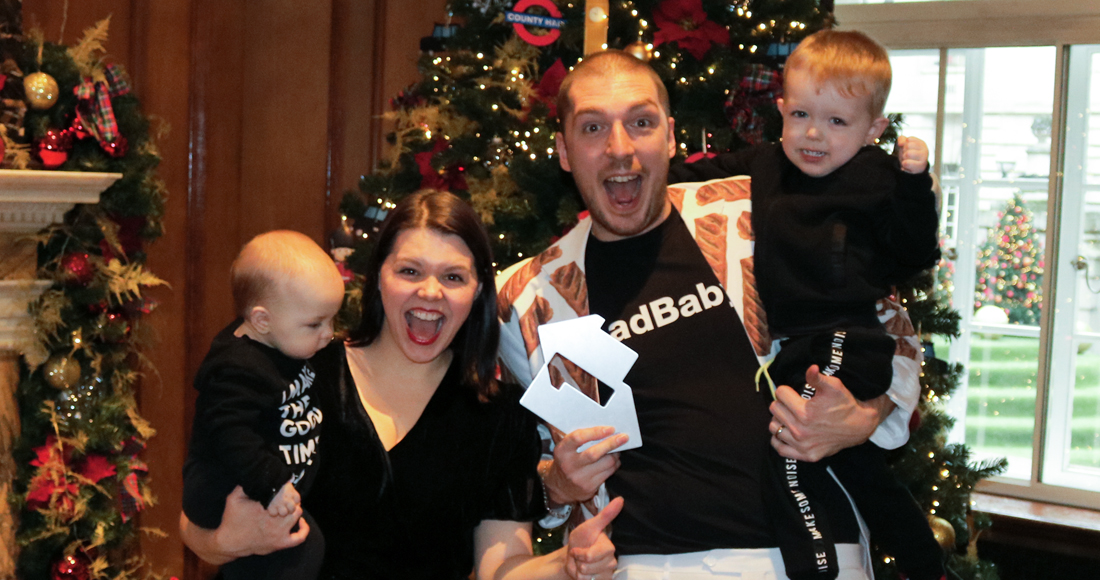
LadBaby began the sausage-roll Christmas-number-one run, Disney+ opened the streaming wars, and Captain Tom walked his garden for the NHS.
COVID-19
2020
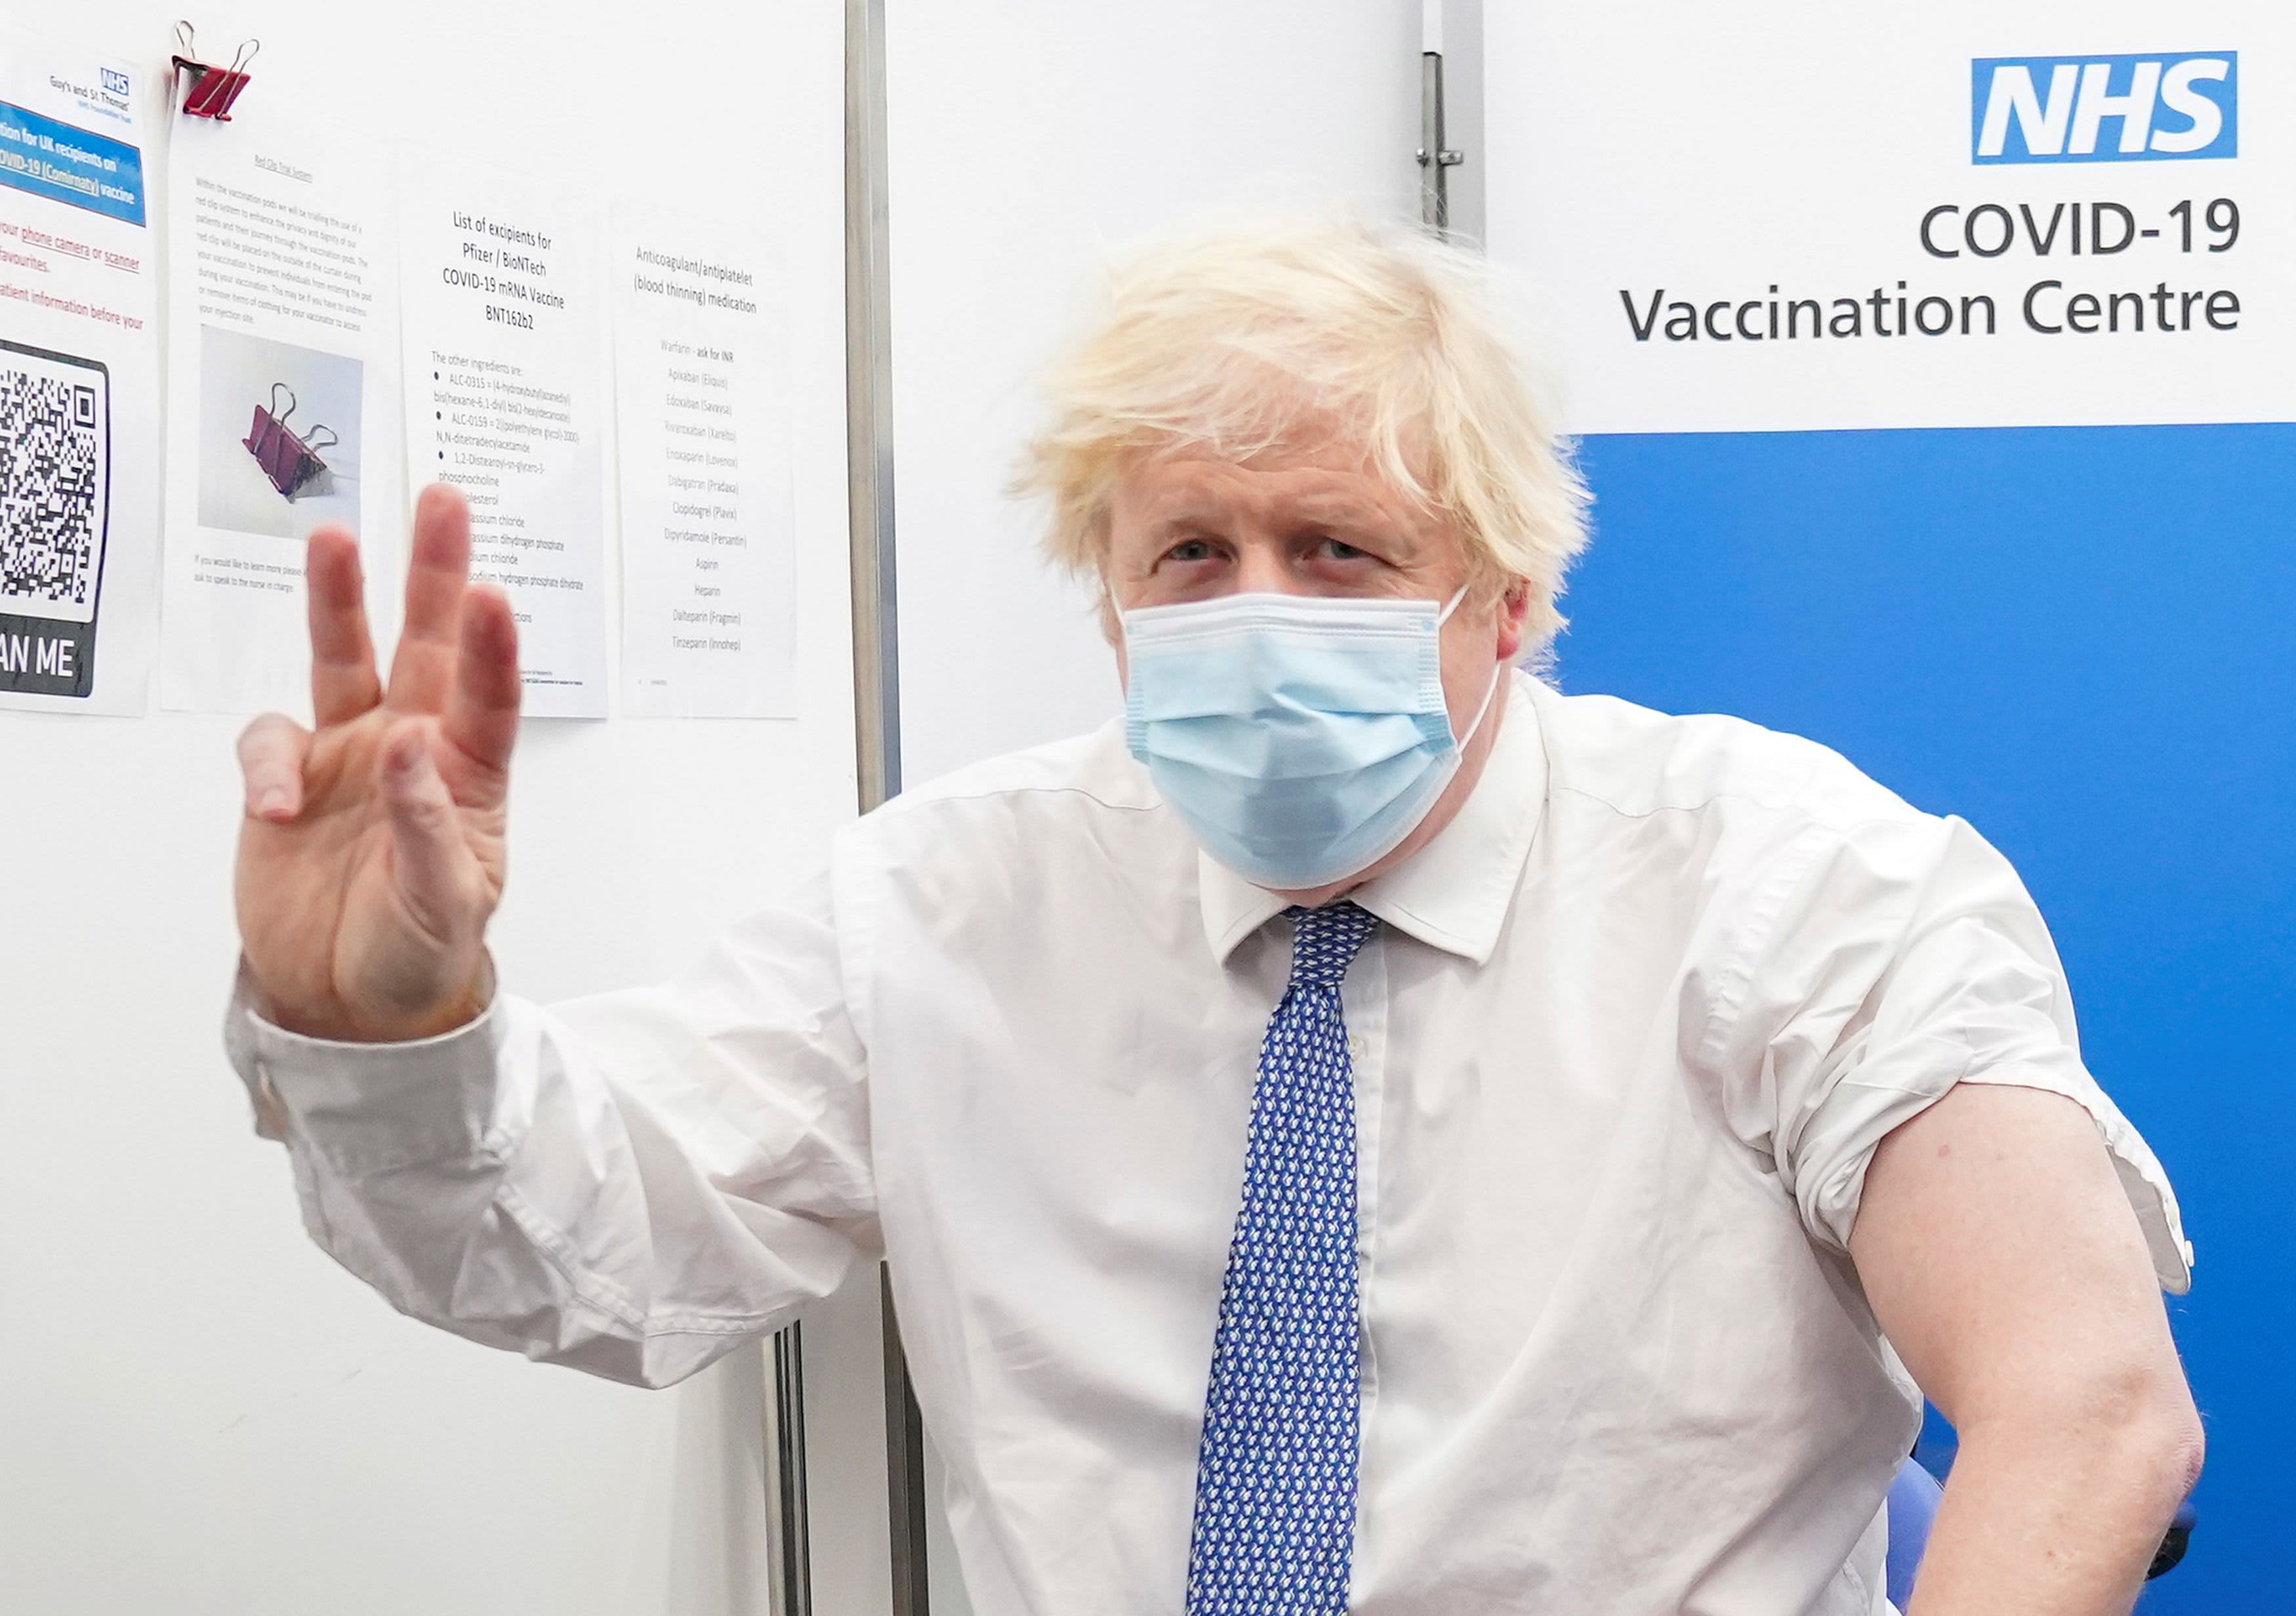
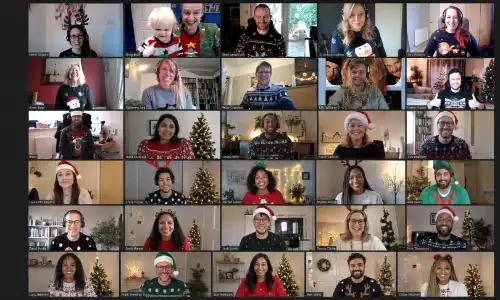
Covid hit in 2020, forcing years of digital adoption into a few weeks. We did what good digital teams were built to do: went fully remote, kept delivering, and helped clients pivot fast. When things got tough, our clients knew they could rely on us to help reshape projects overnight.
US base moves to Greenville, SC
2020
Having started in Boston, MA, in 2020 the US office moved to Greenville, SC in 2020. This strategic move put us closer to clients down the East Coast. Today the US team is serving clients across the from East to West Coast.
The year that tested us, and everyone else
2020
2020 saw unpredictability and many challenges. Projects paused, clients went under, revenue fluctuated, and we had to be more adaptable (and move quicker) than ever before. In some ways, we're still feeling the effects of that year, but we came through it stronger and more resilient than ever.
The AI Era
2021–2025 · Nottingham, Rise & consultancy
Launching Rise, embedding AI, and shifting from agency to digital consultancy.
Creation of Rise
2021
We launched <a href="https://rise.studio/" target="_blank">Rise</a>, a dedicated digital product studio for startups. It's where we back early-stage ideas with the same craft we bring to established brands - a sign of where we think the next decade of work is heading.
Adopting AI
2021
We’ve always been at the cutting edge of technology, so it’s no surprise that AI is already embedded throughout our firm. For us, AI enhances what we do, making our team even more effective.
Shift towards consulting
2021
In 2021, we made a conscious change to our offering, positioning us a digital consultancy rather than an agency. Earned from the maturity of the business and our people, the way we approach problems now, and the IP we've built up over two decades of doing this means we sell expertise far more than just delivery these days.
ChatGPT launches
2022
ChatGPT launched in late 2022 - a landmark moment for publicly available AI tools. And arguably the start of the AI gold rush. It was the first time many people had seen AI in action, and it sparked a wave of interest and experimentation across industries.
Generative image tools
2022
In 2022 DALL-E, Midjourney and Stable Diffusion arrived and creativity shifted. Generative image tools made it possible to create images from text prompts, opening up new possibilities for all, not just designers. It led to a surge in experimentation (to put it mildly), and a new era of AI-assisted creativity.
2021 - 2025 Sporting Moments
2022
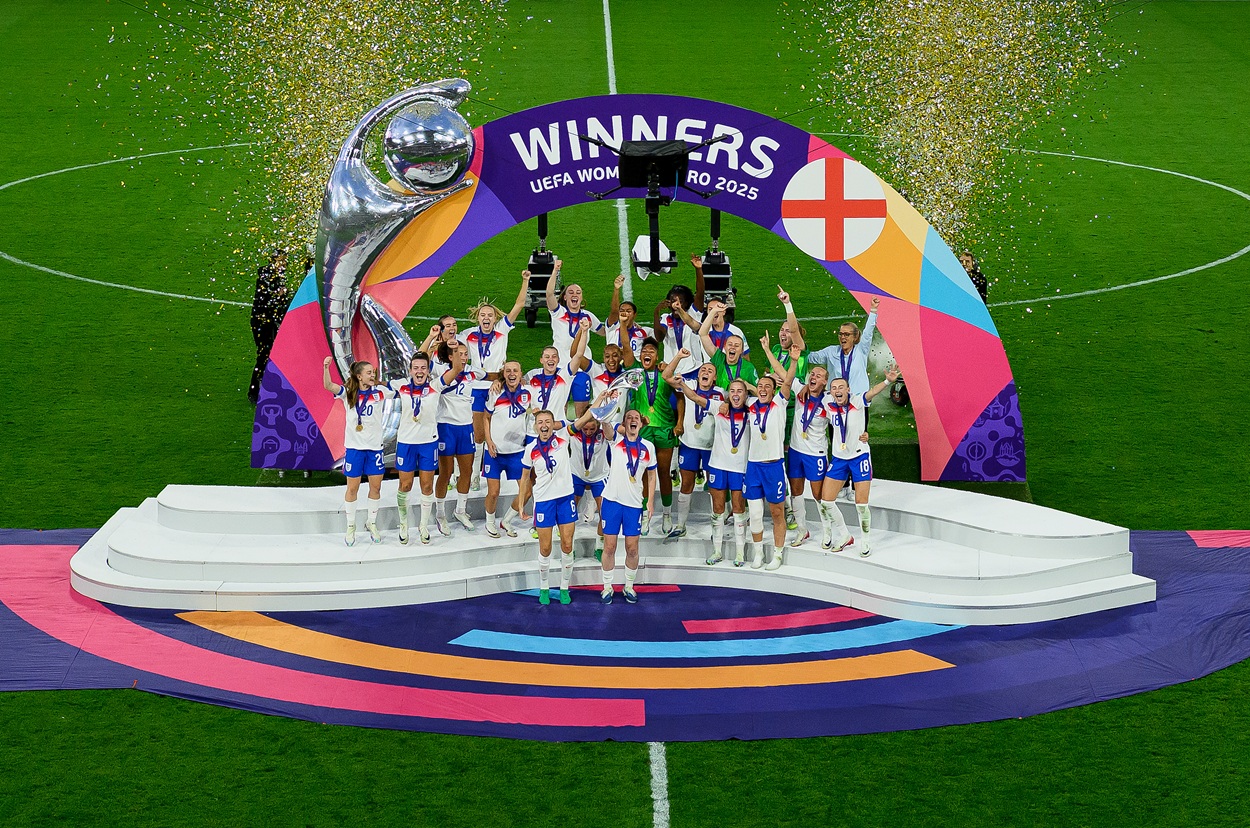
In 2022 the Lionesses won Euro 2022, women's football's breakthrough moment. They then went on to retain it in 2025, further cementing their place in history.
Hottest years on record
2023
In 2023 and 2024 the hottest years on record stacked up. It pushed sustainability up the agenda across our industry - from greener hosting to leaner, lower-carbon digital.
2021 - 2025 Cultural Moments
2023
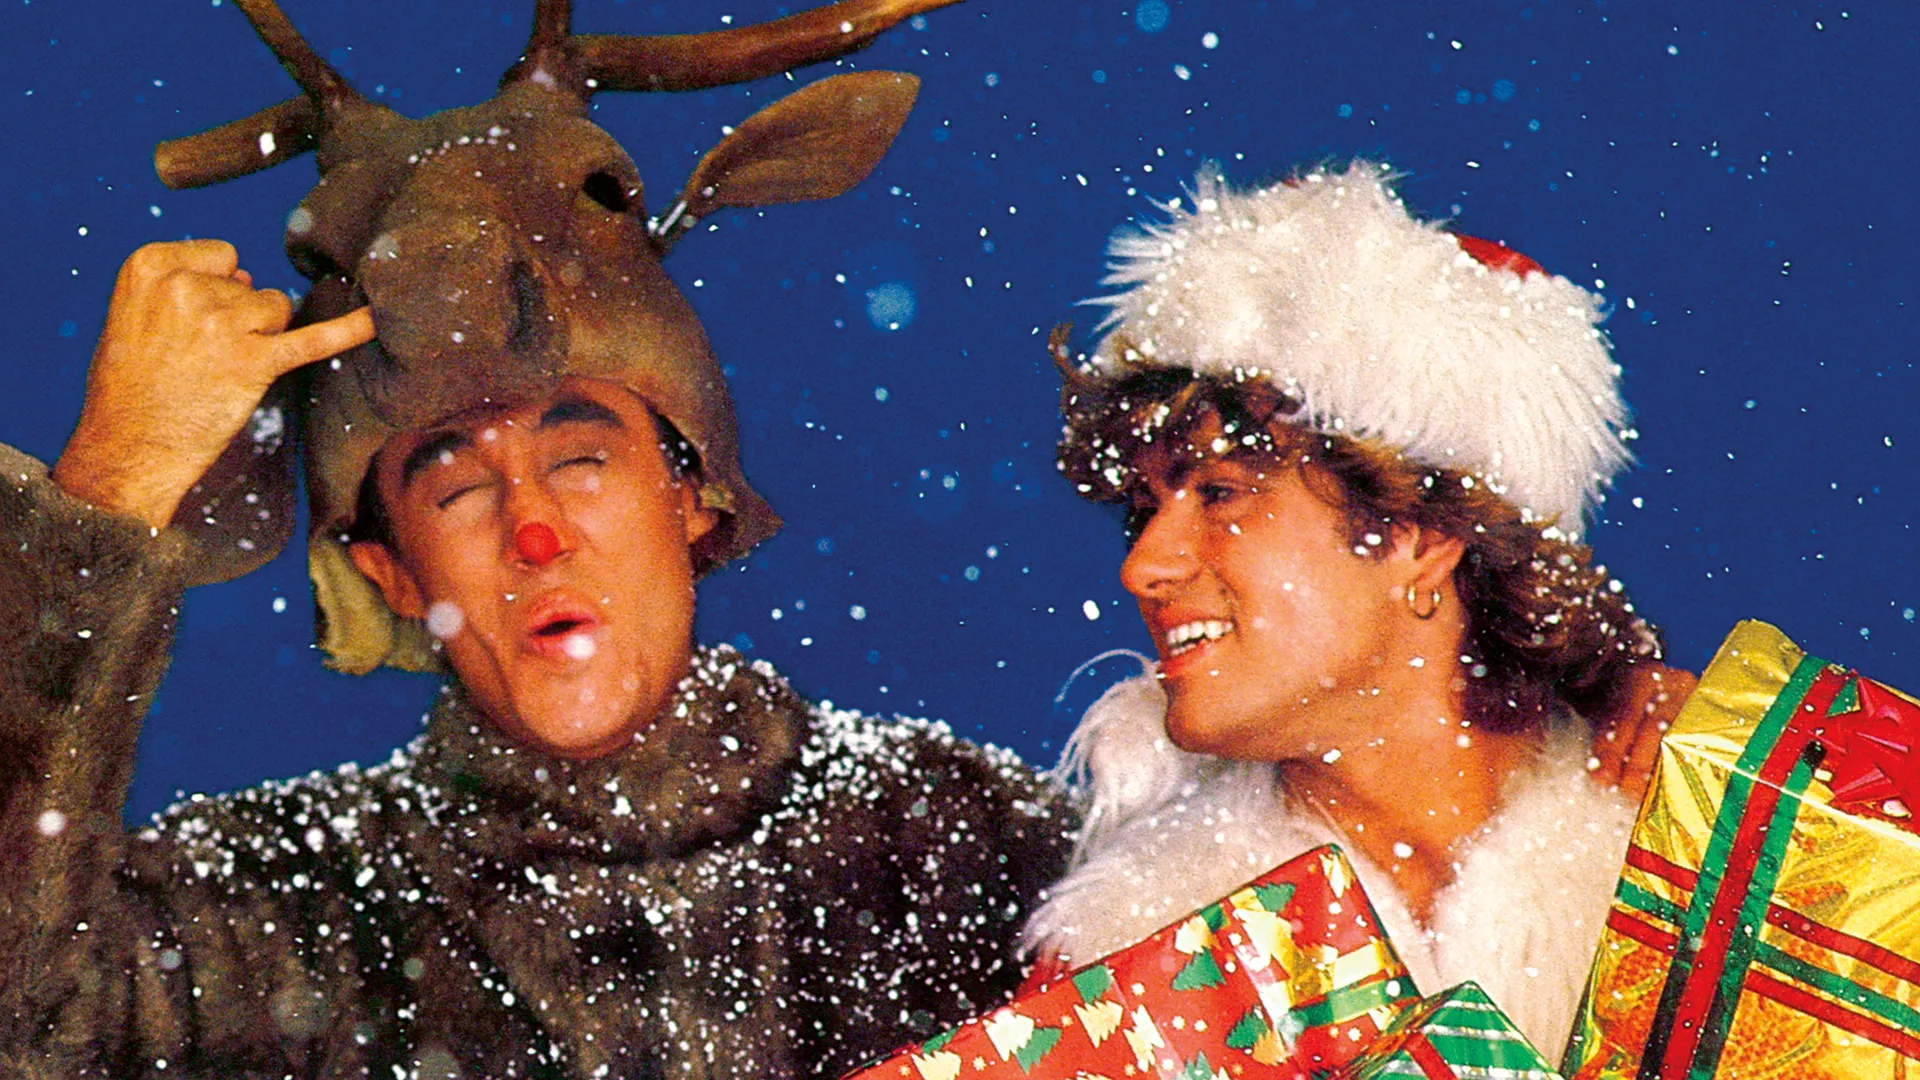
Wham!'s Last Christmas finally hit number one 39 years late, and Barbenheimer revived cinema while strikes put AI centre stage.
Legacy platform debt bites
2024
By 2024 legacy platform debt got painful; you can't bolt AI on. The only way to get the most out of AI is to have a modern, flexible platform that can adapt and evolve with it. The companies that invested in their platforms early are reaping the rewards.
Agentic AI
2025
By 2025 agentic AI - assistants that act, not just answer - arrived. It was a step-change in how AI could be used, and the start of a new era in human-computer interaction.
The next five years
Most predictions draw a straight line up and to the right. I'm not so sure. Here’s two bets we’re putting out there…
Our first bet is dull but firm: the winners won't have the best AI, they'll have changed how they work fast enough to use it. When capability stops being a constraint, the thing that matters then becomes whether organisations can absorb it.
The second I'd stake the most on. When everyone has the same models, the technology stops being a differentiator. If "decent" is now something anyone can produce in an afternoon, then decent is the floor, not the ceiling.
The cost of mediocrity has collapsed - the market is already flooded with it – and the "good enough" trap we've banged on about for years gets worse, not better.
So, value lies in what the tools can't copy: judgement, taste, trust, and accountability. For B2B services especially, the basis of value migrates from deliverables to outcomes.
If clients can make the artefact themselves, they're paying you to know which thing is worth making and to be accountable when it ships. Harder to sell, sure, but a much better business to be in.
ChatGPT
10 predictions for the future of business, work, economies, tech and the world by 2031
1. AI agents become normal at work, but not fully trusted
By 2031, most large firms will use AI agents to handle repeat tasks across sales, service, finance, HR, legal, product and operations. But the winners will not be the firms that let AI run loose. They will be the ones with clear rules, audit trails, human approval points and strong AI security.
Source: Gartner - Top strategic technology trends for 2026
https://www.gartner.com/en/articles/top-technology-trends-2026
2. Jobs will change more than they vanish
The next five years will bring real job loss in some areas, but the bigger story will be task change. The World Economic Forum expects 22% of jobs to be disrupted by 2030, with 170 million roles created and 92 million displaced - a net gain of 78 million. That sounds positive, but it will feel messy for people in roles built around admin, basic analysis, content production or routine support.
Source: World Economic Forum - Future of Jobs Report 2025
https://www.weforum.org/press/2025/01/future-of-jobs-report-2025-78-million-new-job-opportunities-by-2030-but-urgent-upskilling-needed-to-prepare-workforces/
3. Skills-based hiring becomes more common
Degrees will still matter, but less than proof of skill. Employers will care more about whether someone can work with AI, solve problems, learn fast and apply judgement. The World Economic Forum says employers expect 39% of key skills to change by 2030. The OECD also argues that firms face talent shortages while many workers have skills that are not being fully used.
Source: World Economic Forum - Jobs of the future and the skills you need
https://www.weforum.org/stories/2025/01/future-of-jobs-report-2025-jobs-of-the-future-and-the-skills-you-need-to-get-them/
4. Small teams will build what used to need whole departments
AI-native software tools will make it easier for small teams to build products, services, campaigns, dashboards and internal systems. This will not remove the need for engineers, designers or product people, but it will raise the bar. The best people will move from “doing the task” to setting direction, checking quality and joining systems together.
Source: Gartner - Top strategic technology trends for 2026
https://www.gartner.com/en/newsroom/press-releases/2025-10-20-gartner-identifies-the-top-strategic-technology-trends-for-2026
5. Trust becomes a core product feature
By 2031, customers, regulators and business buyers will ask tougher questions: Was this made by AI? Can the data be checked? Who is liable if it fails? Is this content real? That means provenance, cyber controls and AI risk management will become part of brand trust, not just IT work.
Source: Gartner - Top strategic technology trends for 2026
https://www.gartner.com/en/articles/top-technology-trends-2026
6. Power and compute become board-level issues
AI will not just be a software issue. It will be an energy, property and supply issue. The IEA says data centre electricity use rose 17% in 2025, faster than total global electricity demand, and its 2025 outlook says data centre and AI power demand is growing fast in advanced economies and China. By 2031, access to cheap, stable, clean power will shape where AI-heavy firms place data centres and offices.
Source: International Energy Agency - Data centre electricity use surged in 2025
https://www.iea.org/news/data-centre-electricity-use-surged-in-2025-even-with-tightening-bottlenecks-driving-a-scramble-for-solutions
7. Robots move from factories into more daily operations
Physical AI will grow in warehouses, logistics, farming, construction, hospitals and care settings. It will be slower than the hype in homes, but faster in controlled settings where the task is clear. The International Federation of Robotics says 542,000 industrial robots were installed in 2024, more than double the number from ten years earlier, and Gartner has named Physical AI as one of its 2026 tech trends.
Source: International Federation of Robotics - Global robot demand in factories doubles over 10 years
https://ifr.org/ifr-press-releases/news/global-robot-demand-in-factories-doubles-over-10-years
8. The global economy grows, but feels more fragile
I expect modest growth, more shocks and sharper gaps between winners and losers. The IMF projected global growth of 3.1% in 2026 and 3.2% in 2027 in its April 2026 outlook, below pre-pandemic averages. Firms with strong data, AI use, pricing power and access to capital will pull ahead. Firms with weak margins, high debt or slow tech use will fall behind.
Source: International Monetary Fund - World Economic Outlook, April 2026
https://www.imf.org/en/publications/weo/issues/2026/04/14/world-economic-outlook-april-2026
9. Trade stays global, but firms build for risk, not just low cost
Companies will not stop using global supply chains. But they will build more backup options, more regional supply, and more trusted suppliers. Trade policy uncertainty is still high, and the WTO says 2026 will not repeat the one-off boost from firms bringing purchases forward ahead of policy shifts. By 2031, supply chain strength will be a selling point, not just an operations metric.
Source: World Trade Organization - Global Trade Outlook and Statistics, March 2026
https://www.wto.org/english/res_e/booksp_e/gtos0326_e.pdf
10. Climate adaptation becomes a normal business cost
By 2031, more firms will spend on heat protection, flood planning, water security, stronger sites, backup power and insurance changes. This will hit property, retail, manufacturing, food, travel and logistics. Munich Re says natural disasters caused about US$224bn in global losses in 2025, with weather disasters making up 92% of total losses and 97% of insured losses. That cost pressure will push climate adaptation into everyday planning.
Source: Munich Re - Natural disaster figures 2025
https://www.munichre.com/en/company/media-relations/media-information-and-corporate-news/media-information/2026/natural-disaster-figures-2025.html
Overall call
By 2031, the best firms will not be “AI firms”. They will be firms that learn faster, run leaner, build trust into their systems and treat energy, talent and risk as part of the same plan.
Claude
Claude's Ten predictions for 2031
1. The great deceleration carries on
The world doesn't get its growth mojo back. The IMF has global growth at 3.1% in 2026 and 3.2% in 2027, slower than its recent pace of about 3.4% and below its 2000–19 average of 3.7%, settling around there for the medium term. Closer to home, UK growth is projected to slow to 0.8% in 2026 before recovering to 1.3% in 2027.
The point that matters for you: the AI productivity miracle everyone's banking on probably won't show up in the macro numbers by 2031. The drags are structural and slow, and AI's lift is real but takes years to diffuse. Growth will have to come from taking share, not riding a tide.
2. AI splits the workforce, it doesn't empty the office
No mass unemployment, and the catastrophe story keeps not happening. The Anthropic study, the IMF's Denmark analysis, and the Stanford AI Index all independently land on no aggregate unemployment signal so far. But the edges are fraying. PwC's barometer, built on more than a billion job ads, finds AI driving a two-track labour market, and the squeeze lands hardest at the bottom. Entry-level job postings in the US are down 35% since early 2023, with new-grad unemployment at 5.7% and 43% underemployed.
So here's the bit nobody's pricing in: if AI does the junior work, the apprenticeship model quietly breaks. Where do your senior people come from in 2031 if the bottom rungs of the ladder have gone?
3. The AI build-out meets a reckoning, probably a financial one
The numbers have gone properly silly. The five biggest US spenders are guiding to $635–690 billion in combined 2026 capex, with roughly 75% of hyperscaler capex going to AI infrastructure and around $5.2 trillion in cumulative data-centre investment through the end of the decade. More tellingly, capex intensity is now running at over a third of revenue, more than double the 15% peak of the 1990s internet build-out, and free cash flow is turning negative for the first time in 35 years. Then there's the circularity: OpenAI has made roughly $1.5 trillion in cumulative spending commitments against about $13 billion in annual revenue and a $12 billion quarterly loss.
I'm not so sure all of that money is real. A correction or shakeout before 2031 looks more likely than not. That won't mean AI was a con, mind. The Victorian railway mania went bust too, and we still got the railways.
4. Power, not chips, becomes the binding constraint
The story shifts from silicon to substations. The IEA expects data-centre electricity demand to roughly double from 485 TWh in 2025 to 950 TWh in 2030, around 3% of global demand, with data centres making up nearly half of US electricity demand growth to 2030. Now, the honest caveat the breathless coverage skips: globally, data centres account for less than 10% of electricity demand growth to 2030, behind EVs, air conditioning and industrial electrification. The squeeze is local and concentrated, not a worldwide supply crisis.
Expect grid-connection queues, on-site gas, and a genuine nuclear revival, with the pipeline of offtake agreements between data centres and small modular reactors growing from 25GW at the end of 2024 to 45GW. Being able to get power, in the right place, becomes a competitive variable.
5. The demographic bill lands, and there's no dodging it
This is the megatrend that gets least airtime and arguably matters most. 2025 was long pencilled in by demographers as the turning point: the working-age population in OECD countries is now starting to fall, and is projected to keep falling through to 2060. Every OECD member is projected to see its working-age population decline between 2030 and 2050, and one analysis warns over 85 million jobs could go unfilled globally by 2030. The OECD's gloomy line: at current productivity rates, GDP-per-capita growth across the OECD slows by about 40%, from 1% a year to 0.6%.
Labour shortage replaces job shortage. This, far more than any sci-fi takeover narrative, is the real reason automation gets pulled forward. Firms won't have the people.
6. Robots step off the screen and onto the warehouse floor
Physical AI stops being a demo and starts being a line item, in narrow settings. Counterpoint counted 16,000 humanoid robots installed globally in 2025, with cumulative installations projected to top 100,000 by 2027, and payback periods down to around 1.3 years. The deployments are real now, with Figure's robots contributing to building more than 30,000 BMW X3 vehicles over an 11-month deployment.
But keep your expectations in check. The general-purpose humanoid remains aspirational, and today's deployments work by narrowing the task scope aggressively. The awkward jobs (sub-millimetre precision, hazardous environments, full production-cycle speeds) stay out of reach. The robot butler making your tea stays a pitch deck. The robot moving totes in a logistics shed becomes ordinary.
7. Globalisation reshuffles rather than dies
The "end of globalisation" headlines are overcooked. China's grip is loosening, with its share of total US imports falling from 22% in 2017 to 16% in 2022, but this hasn't been accompanied by reshoring. The slack was picked up by Vietnam, Mexico, India, Taiwan and Canada. The redirection is enormous: US goods imports from Vietnam surged from about $49 billion in 2018 to $194 billion in 2025, while imports from Mexico rose from $347 billion to $535 billion, and US imports and Chinese exports both hit all-time highs in 2025.
As the economists put it bluntly, resilience does not equal reshoring, because firms prefer diversification that keeps cost advantages while cutting geopolitical exposure. So expect "China+1", regional blocs, and supply chains that get more complex and a touch pricier, not simpler or cheaper.
8. Agents become the operating layer, but only for the disciplined few
This one's squarely your patch. The direction of travel is clear: around 40% of enterprise applications will embed task-specific agents, and Gartner expects 80% of customer-service organisations to apply agentic AI. The interface shifts from operating the tool to briefing the agent. And yet the graveyard is enormous. As of early 2026, only 11–14% of enterprise AI agent pilots had reached production at scale, with 86–89% failing to realise durable value, and only 6% qualify as true AI high performers, while 52% cite data quality as the biggest blocker.
Put another way, the gap between the leaders and the "good enough" brigade widens brutally. The winners won't be whoever buys the shiniest model. They'll be the ones who sorted out their data and their governance first, which is the deeply unsexy work everyone wants to skip.
9. The cheap-money era is properly over, and the bill arrives
Debt has piled back up without the rate cushion that softened the last decade. Global public debt rose to just under 94% of GDP in 2025 and is set to hit 100% by 2029, a year earlier than projected. Governments and companies are set to borrow $29 trillion from bond markets in 2026, 17% more than in 2024 and double a decade ago. The painful difference this time: high deficits are no longer accompanied by accommodative interest rates, and borrowers are shifting to shorter maturities, which raises refinancing risk.
For mid-market firms, that means the cost of capital stays stubbornly higher than the 2010s trained everyone to expect, and governments have far less room to cushion the next shock.
10. Seeing stops being believing
Digital trust takes a battering. A projected 8 million deepfakes will be shared in 2025, up from 500,000 in 2023, and you've probably seen the eye-catching Europol line that up to 90% of online content may be synthetically generated by 2026. I'd treat that last stat with a pinch of salt, since it lumps all AI-assisted content in with malicious fakes, but the direction is undeniable. Media experts are already talking about a collapse of trust online, where what's fake looks real and what's real looks fake.
For B2B this isn't abstract. Deepfakes are increasingly generated in real time and injected into video feeds during onboarding, turning identity and verification into a material risk for any business relying on authentic digital interactions. Your brand and your customers' trust become an attack surface, and provenance and verification become a genuine market.
The through-line, if you want one: for all the AI noise, the boring stuff decides who wins. Power, people, money, and clean data. The firms that obsess over those while everyone else chases the demo will be the ones still standing in 2031.
Sources
1. Growth
2. Jobs
3. AI capex
4. Energy
5. Demographics
6. Robots
7. Trade
8. AI adoption and agents
9. Debt
10. Synthetic media
Gemini
Gemini's 10 Predictions: 2026–2031
Technological & World Perspective: The "Agentic" Shift
- From Chatbots to Autonomous Agents: We are moving away from tools you prompt to AI agents you manage. By 2031, AI agents will routinely handle complex, multi-step workflows independently—from supply chain logistics to personalized medical triage.
- The Green Grid Lock-in: Climate change ceases to be a future warning; adaptation is now a line item on every budget. Expect massive infrastructure overhauls as grids struggle to support both the energy-hungry AI data centers and the accelerating transition to electric transport and heating.
- Biotech and Longevity: Breakthroughs in mRNA tech, CRISPR gene-editing, and personalized medicine will begin shifting healthcare from reactive treatment to proactive, algorithmic prevention.
Economic & Political Perspective: Fragmentation & Regulation
- The Age of "Friend-Shoring": Globalization isn't dead, but it has re-formed into geopolitical blocs. Supply chains will prioritize political alignment and resilience over the absolute lowest cost.
- Sovereign AI and Tech Nationalism: Governments will increasingly view AI capabilities and semiconductor manufacturing as matters of national security, leading to heavy regulation, digital borders, and aggressive anti-monopoly scrutiny of Big Tech.
- Structural Economic Shifts: As automation reshapes white-collar work, governments will face intense pressure to address wealth disparity, potentially piloting forms of universal basic income (UBI) or "data dividends" funded by tech productivity gains.
👥 The Stakeholder Impact: Who Wins, Who Adapts?
👤 Humans: The Search for Authenticity
As synthetic media and AI interactions become indistinguishable from reality, the premium on human authenticity will skyrocket.
- The Trust Premium: Human-centric, unscripted, and analog experiences (live events, hand-crafted goods, face-to-face community) will become luxury commodities.
- The Cognitive Load: Mental health will center around "digital detoxing" and managing the cognitive fatigue of living in a hyper-optimized, hyper-paced digital reality.
🏢 Employers & Businesses: Decentralized & Resilient
The blueprint for a successful company is being rewritten.
- The Lean Giants: We will see the rise of the "micro-multimonopoly"—incredibly lean businesses utilizing AI networks to achieve massive scale with fractions of the traditional headcount.
- Skills-Based Architecture: Employers will abandon rigid job titles in favor of dynamic, skill-based project pooling. If your company cannot re-skill its workforce on the fly, it will stagnate.
💼 Employees: The "Portfolio" Career
The concept of a linear career path is rapidly dissolving.
- The Rise of the Fractional Worker: More professionals will operate as "fractional" experts, renting out highly specialized skills to multiple companies simultaneously via AI-augmented platforms.
- The New Core Skills: Technical coding is losing its premium to curation, prompt architecture, empathy, and systems thinking. The most valuable asset an employee can have is "learnability"—the speed at which they can absorb new tools.
🎗️ Charities & Non-Profits: Doing More with Less (and New Squeezes)
The third sector will find itself caught between unprecedented capability and intense competition for funding.
- Hyper-Personalized Philanthropy: Charities will use advanced predictive models to match donors with hyper-specific causes, proving the direct ROI of a donation down to the penny.
- The Funding Squeeze: Corporate giving may fluctuate as businesses invest heavily in their own technological transitions. Charities will have to heavily lean on automated operations to keep overhead low.
- New Frontlines: Non-profits will be forced to tackle entirely new crises, such as technological displacement of workers and the relocation of communities due to climate volatility.
📊 Summary: The 5-Year Outlook Matrix
| Stakeholder | Biggest Opportunity | Greatest Risk |
|---|
| Humans | Unprecedented access to personalized health and learning. | Digital isolation and a crisis of purpose. |
| Employers | Hyper-efficiency and rapid scalability via AI agents. | Severe cyber-vulnerabilities and cultural fragmentation. |
| Employees | Freedom from mundane tasks; rise of autonomous work. | Rapid skill obsolescence and wage polarization. |
| Charities | AI-driven operational efficiency and global outreach. | Donor fatigue and navigating systemic "AI inequality." |
Ultimately, the next five years will reward the adaptable over the optimized. The businesses and individuals who thrive won't be the ones who built the perfect 10-year plan in 2025, but those who build the flexibility to pivot every quarter.
Perplexity
Perplexity's
Here are 10 plausible predictions for the next 5 years:
-
AI will become a standard layer in most office jobs, not a separate tool, with people using it for writing, analysis, customer support, coding, and scheduling.
-
Many employers will shift from hiring for fixed roles to hiring for adaptable skills, because job tasks will keep changing faster than job titles.
-
The biggest career premium will go to people who combine domain expertise with AI fluency, rather than people who rely on either alone.
-
Cybersecurity spending will rise sharply, because more business processes will be digital and AI will also make scams and attacks more sophisticated.
-
Economic growth will remain uneven, with periods of weaker consumer demand, higher borrowing costs than the 2010s, and more pressure on profit margins.
-
Businesses will put more emphasis on resilience than on pure efficiency, meaning more backup suppliers, more cash discipline, and more scenario planning.
-
Political debate will stay volatile, with more focus on immigration, taxation, housing, industrial policy, defence, and the cost of living.
-
Charities will face higher demand for services but tougher fundraising, so the strongest organizations will be those that can prove impact clearly and operate leanly.
-
Remote and hybrid work will not disappear, but employers will tighten rules around performance, collaboration, and in-person time for roles that need it.
-
The most successful organizations will treat change as normal, building systems and cultures that can adapt every year rather than every decade.
A simple way to sum it up: the next 5 years will reward adaptability more than stability.
Unfashionable to say in 2026, which is rather the point.
Start the conversation →